Entry in Choosing Deductibles for Collision and Comprehensive
$500 vs. $1,000 Full Coverage Deductible: How to Decide
Compare a $500 vs. $1,000 deductible for full coverage car insurance. See how premium savings, out-of-pocket risk, and break-even math affect your decision.
By Chris Delgado · Editor
Published
Answer in brief
Choosing between a $500 and $1,000 deductible comes down to comparing upfront premium savings against your ability to absorb out-of-pocket loss after an accident. According to data from the Insurance Information Institute, increasing physical damage deductibles can reduce comprehensive and collision premiums by substantial margins. Drivers who maintain a dedicated emergency reserve often come out ahead with a $1,000 deductible, while those living on a tighter cash cushion benefit from the greater predictability of a $500 threshold.
How Deductibles Function in Full Coverage Auto Insurance
When you purchase what full coverage car insurance actually means, you are pairing liability coverage with two physical damage protections: collision coverage and comprehensive coverage. Unlike liability insurance, which pays for damage or injuries you cause to third parties without any deductible required from you, physical damage coverages require you to choose a specific deductible. This deductible represents the pre-agreed dollar figure subtracted from your claim payout whenever your vehicle requires repairs or is declared a total loss.
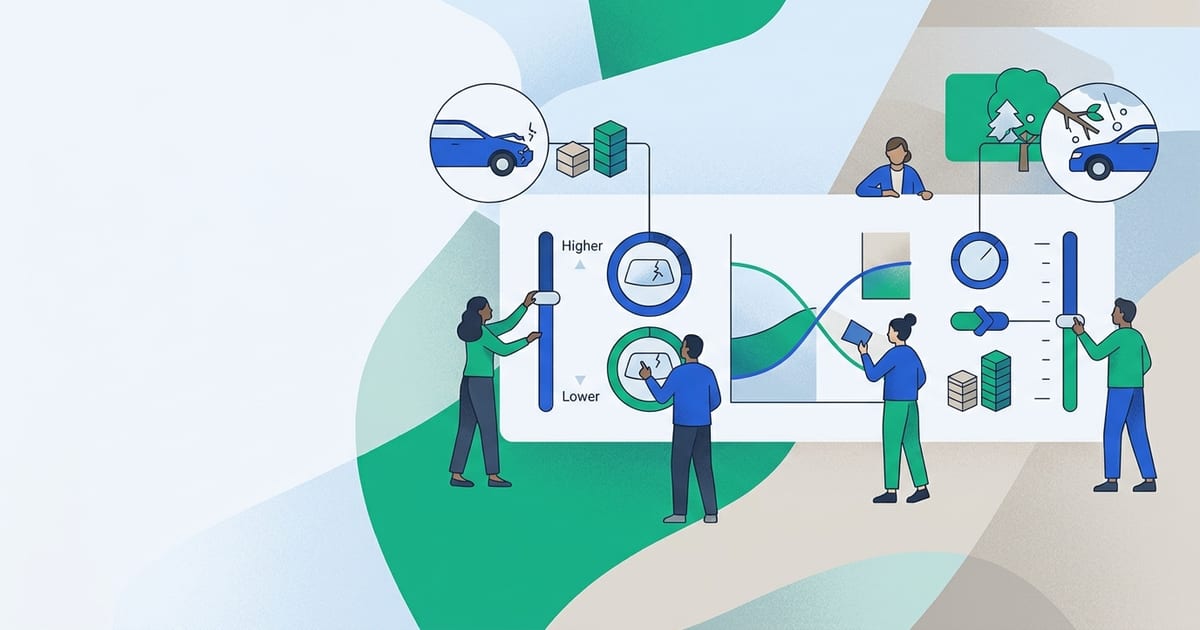
Each physical damage coverage carries its own separate deductible. You can hold a $500 deductible on collision—which triggers when your car hits another vehicle, a tree, a guardrail, or a pothole—and select a different deductible on comprehensive, which covers events outside your driving control, such as hail storms, animal impacts, falling tree branches, or vehicle theft. However, many drivers align both at either $500 or $1,000 to keep their risk management straightforward. Understanding the trade-off between your regular premium and your sudden out-of-pocket exposure is the core of selecting the right balance on our deductibles guide.
The Premium Savings: $500 vs. $1,000 Deductibles
Insurers reward policyholders who assume greater upfront risk because higher deductibles eliminate small, nuisance claims and lower the insurer's ultimate claim payouts. The National Association of Insurance Commissioners (NAIC) reported that the countrywide average auto insurance expenditure reached $1,281 in 2023, with a combined average premium of $1,438. The physical damage portion of that expenditure—covering collision and comprehensive—represents a major portion of your overall bill.
| Deductible Option | Typical Premium Reduction | Illustrative Annual Physical Damage Cost | Out-of-Pocket Risk Per Claim | Break-Even Horizon |
|---|---|---|---|---|
| $200 (Baseline) | 0% (Baseline rate) | $800 – $1,100 | $200 | Baseline |
| $500 Deductible | 15% to 30% reduction vs. $200 | $560 – $770 | $500 | 12 to 18 months |
| $1,000 Deductible | 40% or more reduction vs. $200 | $450 – $620 | $1,000 | 24 to 36 months |
According to the Insurance Information Institute, shifting from a low $200 deductible to a $500 deductible can cut your collision and comprehensive costs by 15% to 30%. Moving up to a $1,000 deductible can reduce physical damage premiums by 40% or more. On an illustrative policy where physical damage coverage costs $900 annually, shifting from $500 to $1,000 often yields between $150 and $220 in net annual savings. Those savings repeat every single year that you avoid filing an at-fault or single-vehicle physical damage claim.
Four Steps to Determine Your Optimal Deductible
- 1
Evaluate Your Liquid Emergency Savings
Non-profit consumer advocates at United Policyholders stress that your insurance deductible should never exceed the cash immediately available in your bank account. If an unexpected $1,000 debit card payment to an auto repair shop would cause missed utility payments or high-interest credit card debt, stick to a $500 deductible.
- 2
Review Financing and Lease Contracts
If you finance or lease your vehicle, your lender is listed as the loss payee. Many financing agreements explicitly mandate a maximum allowable deductible—frequently capped at $500 or $1,000. Selecting an unauthorized $1,500 or $2,500 deductible could violate your financing terms.
- 3
Assess Your Driving Environment and Mileage
Review your daily exposure. Drivers with long highway commutes, crowded street parking, or residences in storm-prone hail belts face elevated comprehensive and collision frequencies, making a lower $500 deductible more reassuring.
- 4
Obtain Side-by-Side Premium Quotes
Deductible discounts vary widely across insurance companies. Check how to compare full coverage car insurance quotes so you can examine identical liability limits with both $500 and $1,000 physical damage deductibles.
When to Select a $500 Deductible
A $500 deductible remains the standard benchmark for American drivers for good reason. It provides a comfortable middle ground between affordability and claim-time safety. You should lean toward a $500 deductible if you have less than $1,500 in dedicated liquid cash reserves, if you commute through dense metropolitan traffic with higher accident frequency, or if your auto loan contract strictly requires deductibles of $500 or lower. Paying a slightly higher annual premium is worthwhile when an unanticipated repair bill would otherwise disrupt your family budget.
When a $1,000 Deductible Delivers Superior Value
Opting for a $1,000 deductible is an effective financial strategy for drivers with stable emergency reserves and clean driving histories. As vehicles age and their actual cash value depreciates, paying elevated premiums for low deductibles yields diminishing returns. Consumer guidance from the Insurance Information Institute notes that when the annual cost of physical damage coverage approaches 10% of your car's market value, reducing coverage costs or raising deductibles helps preserve your overall net worth. If you can comfortably wire or charge $1,000 following an incident, the compounding annual premium savings from a higher threshold make financial sense.
Questions & answers
Do I have to pay my full coverage deductible if an accident is not my fault?
If another driver is clearly at fault and their insurer accepts liability, their property damage liability coverage should pay for your repairs without any deductible. However, if fault is disputed or their insurer delays payment, you can file under your own collision coverage, pay your deductible upfront, and allow your insurer to recover that deductible on your behalf through subrogation.
Can I choose different deductibles for collision and comprehensive?
Yes. Most insurers allow you to separate deductible tiers. For example, some drivers select a $1,000 collision deductible to maximize premium savings while maintaining a lower $250 or $500 comprehensive deductible to protect against frequent glass claims, storm damage, or animal collisions.
What happens if repair costs are lower than my deductible?
If your repair estimate is $400 and your deductible is $500, your insurance policy will not issue a payout. Filing a claim in this scenario creates a record on your claims history without providing any reimbursement, which is why minor scuffs are generally best paid out of pocket.
How does my deductible apply if my car is declared a total loss?
In a total loss scenario, you do not write a check to the insurance company. Instead, the insurer calculates the actual cash value of your vehicle immediately prior to the crash and deducts your chosen deductible from the final settlement check.
Terms: Deductible, Collision coverage, Comprehensive coverage, Actual cash value (ACV), Total loss
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Highway safety — Insurance Information InstituteStatistical dataCrash, injury and fatality trends used to explain why liability and injury coverages cost what they do.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- Understanding your insurance deductibles — Insurance Information InstituteConsumer guidanceHow deductibles apply to collision and comprehensive and how raising them lowers premium.
- Buying tips — United PolicyholdersConsumer guidanceNon-profit guidance on choosing coverage, deductibles and limits, and on handling claims.
- What is covered by a basic auto insurance policy? — Insurance Information InstituteConsumer guidanceDefines bodily injury and property damage liability, MedPay, PIP, uninsured/underinsured motorist, collision, comprehensive and glass coverage.
- How to file an auto insurance claim — Insurance Information InstituteConsumer guidanceSteps after a crash: document the scene, notify the insurer promptly, understand the adjuster's role.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.